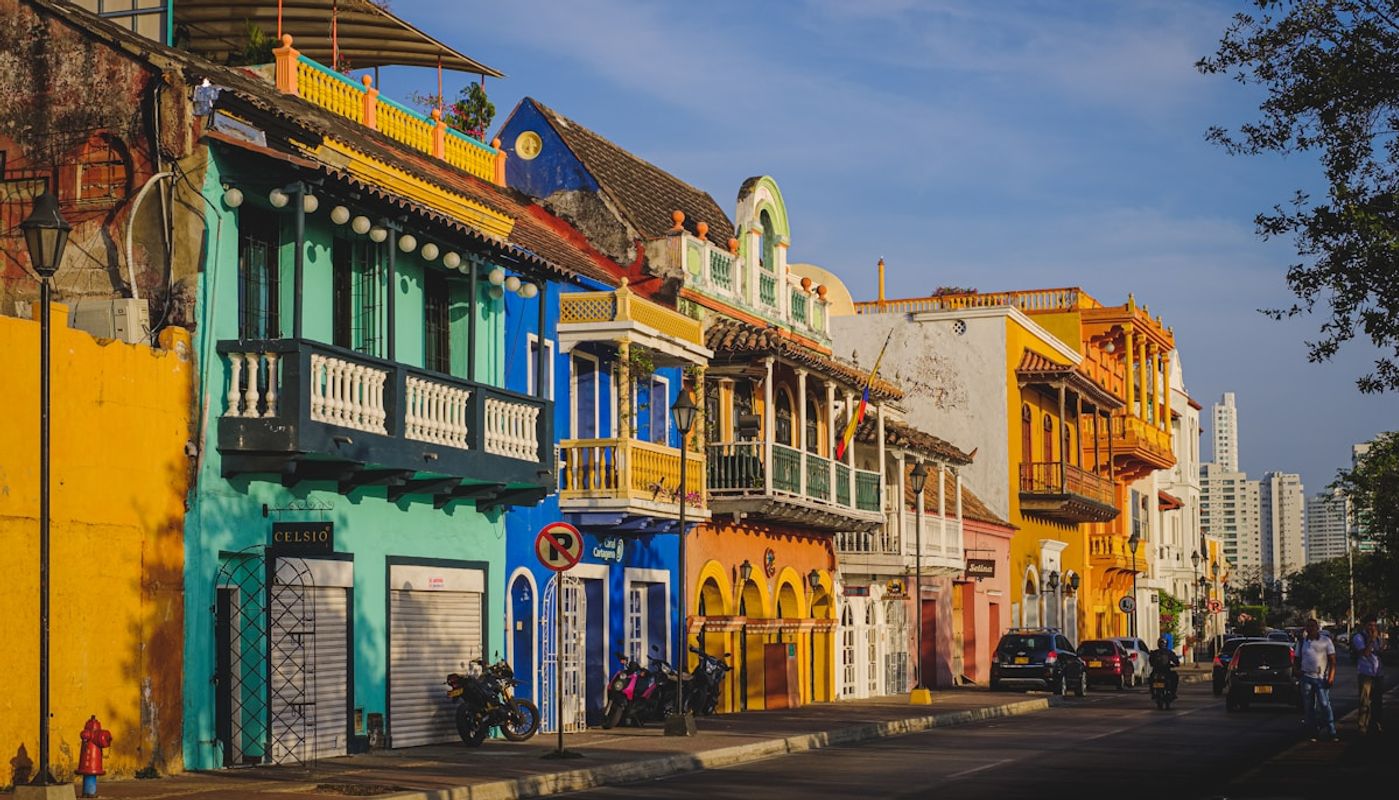
Colombia Rental Income Taxation for Foreign Property Owners
Tax Framework for Foreign Property Owners
Foreign nationals earning rental income from Colombian property are subject to Colombian income tax. The applicable rules depend on whether the owner is a Colombian tax resident or non-resident. The primary law is the Estatuto Tributario (Tax Code), supplemented by annual tax reform laws.
Tax Residency Determination
Under Article 10 of the Estatuto Tributario, you become a Colombian tax resident if you spend 183 or more days in Colombia during any consecutive 12-month period. Tax residents are taxed on worldwide income. Non-residents are taxed only on Colombian-source income.
For foreign property owners who do not live in Colombia (pure investors), non-resident status means only your Colombian rental income is taxable in Colombia.
Non-Resident Rental Income Tax
Non-residents earning rental income from Colombian property face a flat withholding tax rate. The current rate for non-resident rental income is 35% of gross rental income, applied as a final withholding tax.
However, the effective rate can be reduced. Under Article 408 of the Estatuto Tributario, the withholding rate applies to the gross payment. If the property is managed through a Colombian entity or management company, the company can deduct certain expenses before calculating the taxable base, which reduces the effective rate.
Withholding Mechanism
If your tenant is a Colombian company or registered entity, they are required to withhold the tax and remit it to DIAN. If your tenant is an individual or if you use a property management company, the management company should handle the withholding.
It is essential that this withholding happens correctly, because non-residents generally do not file annual Colombian tax returns for rental income that has been fully withheld.
Tax Resident Rental Income
If you are a tax resident (183+ days in Colombia), your rental income is combined with your other worldwide income and taxed at progressive rates. The 2026 progressive rates are expected to continue the bracket structure that reaches up to 39% at the highest income levels.
Tax residents can deduct actual expenses against rental income, including property maintenance and repairs, administration fees, property taxes (impuesto predial), insurance premiums, depreciation of the building (the building portion only, not land, typically at 2.22% annually over 45 years under the Estatuto Tributario), and property management fees.
Capital Gains on Property Sales
Under the Estatuto Tributario, gains from selling real property held for two or more years are classified as "occasional gains" (ganancias ocasionales) and taxed at a flat 15% rate for both residents and non-residents.
If the property is held for less than two years, the gain is treated as ordinary income and taxed at the progressive income tax rates (up to 39% for residents or 35% for non-residents).
The gain is calculated as the sale price minus the acquisition cost. The acquisition cost can be updated using the official inflation adjustment index published by DANE, which reduces the taxable gain in Colombia's inflationary environment.
CBI Comparison
Unlike Turkey, Colombia does not have a property-based citizenship program, so there is no mandatory hold period. However, the two-year rule for preferential capital gains treatment provides a natural incentive to hold.
Investment Repatriation
Foreign investors who registered their original investment through the Banco de la Republica's foreign exchange system (Declaracion de Cambio, Formulario No. 4 for foreign direct investment) can repatriate both the original investment and any returns (rental income, sale proceeds) through the Colombian banking system.
Without proper registration, repatriating large sums can trigger anti-money laundering scrutiny. Register the investment at the time of the property purchase, not after.
Double Taxation Relief
Colombia has double taxation treaties with over 15 countries. The general principle: Colombia has the primary right to tax property income (as the country where the property is located), and your home country must provide a credit or exemption for Colombian taxes paid.
If your country does not have a treaty with Colombia, you may be subject to double taxation. In this case, check whether your home country allows a unilateral foreign tax credit for Colombian taxes paid.
Annual Obligations
Non-residents with only rental income subject to withholding: no annual return is required if withholding was properly applied. Tax residents: must file an annual income tax return (declaracion de renta) by the dates specified in the annual tax calendar published by DIAN (typically August-October of the following year).
All property owners (resident or not): pay the annual impuesto predial (property tax) to the municipality, typically due in the first quarter of the year with early-payment discounts of 5-10%.
For updated tax guidance for foreign property owners in Colombia, Bektu provides resources at https://bektu.com.
Sources
- Estatuto Tributario: https://www.funcionpublica.gov.co/eva/gestornormativo/norma.php?i=6533
- DIAN: https://www.dian.gov.co
- Banco de la Republica (Foreign Exchange): https://www.banrep.gov.co
Sign up to read the rest
Create a free account to keep reading. It only takes a minute.
Considering a developer you read about here?
You cannot walk the land from another country. But you can verify the developer. Bektu contacts them on your behalf and sends you a scored report. They never see who asked.
Search and verify any developerMore from Bektu
Stay a step ahead of the wire transfer
Get the occasional note from Bektu on verifying developers before you commit. No noise, just what matters.
We will never share your email. You can opt out at any time.