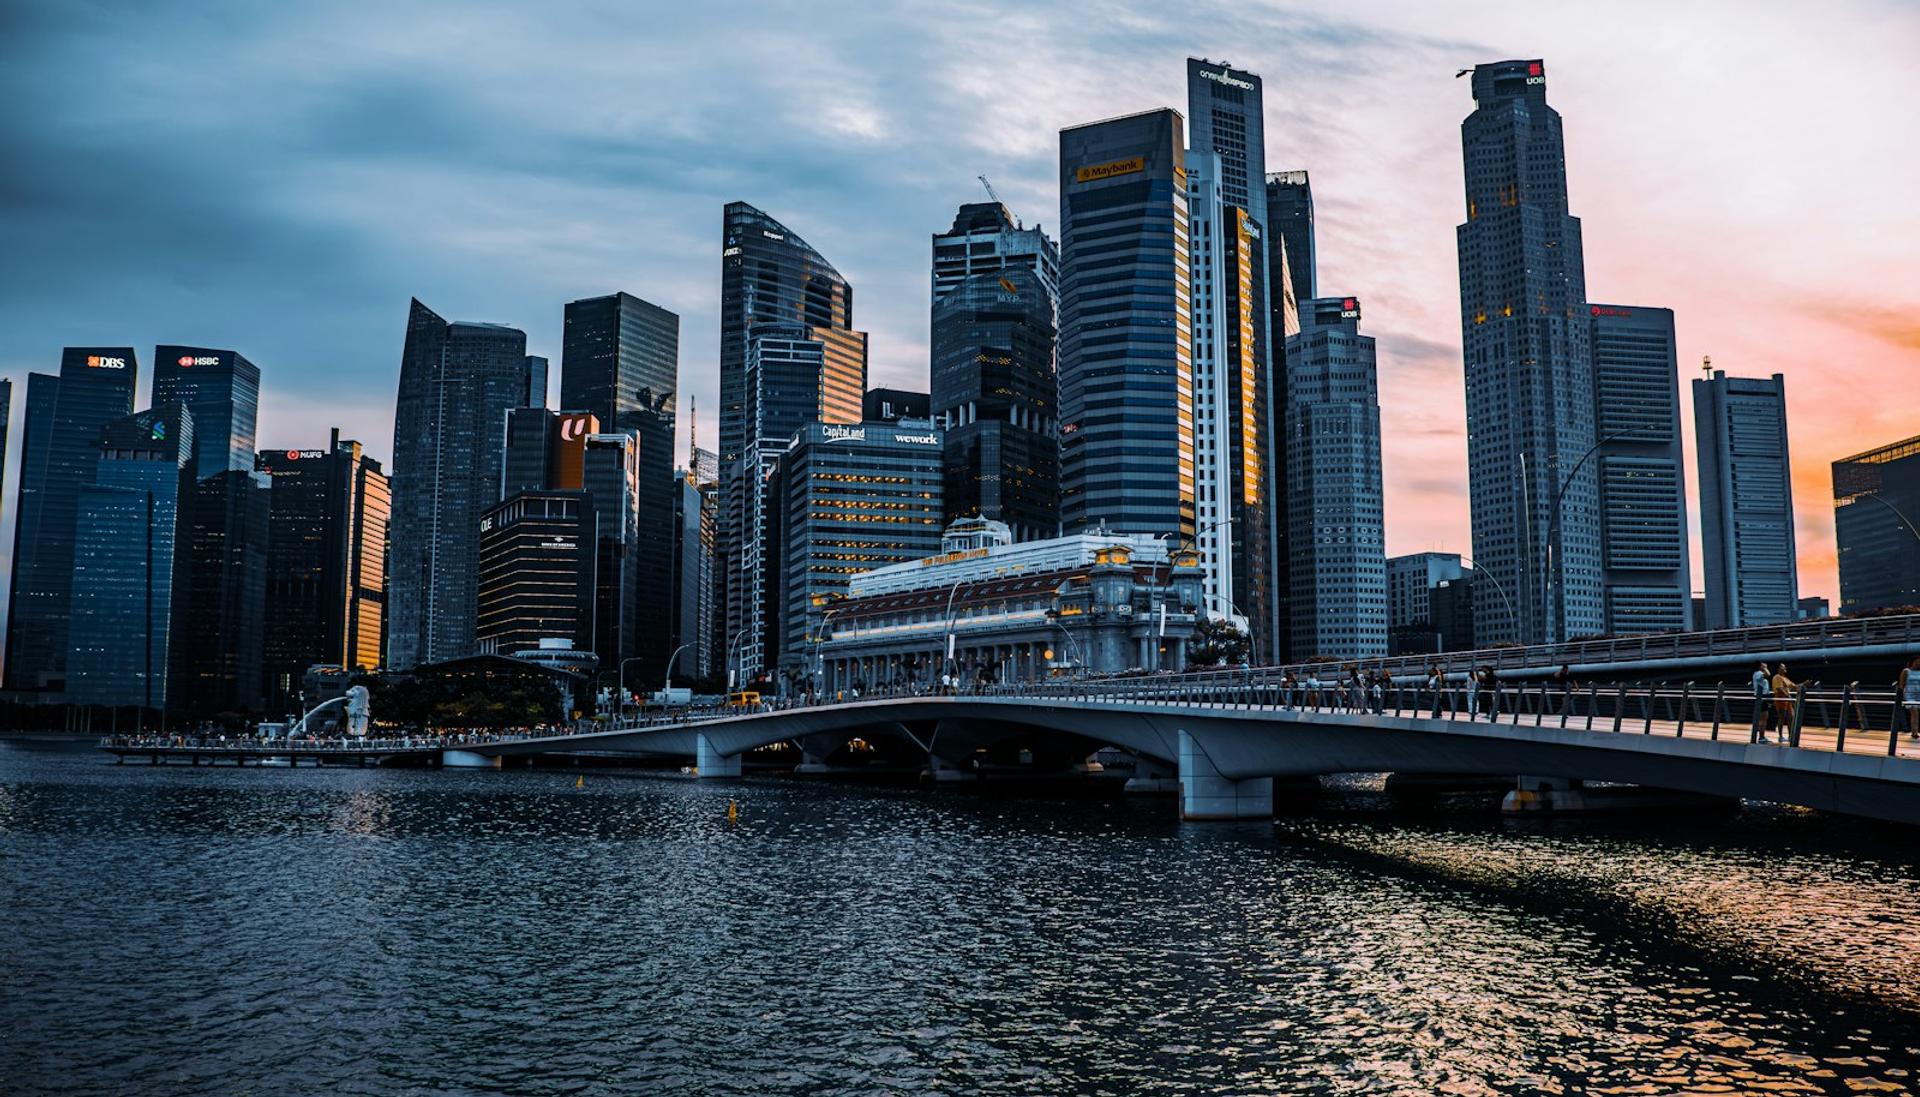
Singapore Private Home Prices Rise 1.4 Percent in the Third Quarter as Prime Districts Fall
Singapore's private residential property price index rose 1.4 percent quarter on quarter in the third quarter of 2026, according to the flash estimate the Urban Redevelopment Authority released on 1 October, almost three times the 0.5 percent increase recorded in the second quarter. The headline conceals a split market: prices in the Core Central Region fell 0.1 percent while the Outside Central Region rose 2.2 percent, and the number of units transacted dropped to 4,296 from 6,148 in the previous quarter.
What it means for a foreign buyer
If you are shopping in the Core Central Region, the asking prices you were quoted over the summer are now ahead of the index. The CCR gained 1.8 percent in the second quarter and gave back 0.1 percent in the third, so a vendor still anchored to a mid-year valuation is holding a number the market no longer supports. Transaction volume is the lever here. At 4,296 units lodged by mid-September, against 6,148 for the whole of the second quarter, there are fewer competing bidders in the room than at any point this year, and year to date the market has absorbed 15,857 units against 19,793 in the same period of 2025. Ask for the last three comparable transactions in the specific project rather than the district, and negotiate against those.
If you are shopping in the Outside Central Region, the position reverses. A 2.2 percent quarterly gain after a 0.1 percent decline in the second quarter means the index has turned inside a single quarter, and you are negotiating into a rising number rather than a soft one. Budget for the asking price to hold. One further point of timing applies to both: these are flash figures, and URA publishes the full third quarter statistics on 23 October, so any transaction you are pricing off the 1.4 percent headline is priced off a number that can still move.
Treat the 1.4 percent as a provisional reading, not a settled one.
What changed
The overall index accelerated from 0.5 percent in the second quarter to 1.4 percent in the third. Non-landed property, the larger part of the market, rose 0.9 percent after falling 0.1 percent in the previous quarter. Landed property rose 2.8 percent, up from 2.5 percent, and is the segment doing most of the work behind the headline.
Within non-landed, the three regions moved in opposite directions from the quarter before. The Core Central Region fell 0.1 percent against a 1.8 percent rise in the second quarter. The Rest of Central Region rose 0.2 percent against a 1.2 percent decline. The Outside Central Region rose 2.2 percent against a 0.1 percent decline. Every one of the three reversed direction, which is unusual in a single quarter and is the reason the regional detail matters more than the index this time.
Companies in Singapore with the most evidence on file
Ranked by BektuScore, which measures how much a buyer can verify about a company from public records. It does not rate build quality or returns.
EMAAR
Developer11 projectsSingapore, Singapore
75Bektu ScoreEL Development Pte Ltd
Developer10 projectsSingapore, Singapore
75Bektu ScoreAllgreen Properties Limited
Developer9 projectsSingapore, Singapore
75Bektu Score
Ask Bektu
Still have a question about buying in Singapore?
Answers come from the records on file, with links to every source.
Considering a developer you read about here?
You cannot walk the land from another country. But you can verify the developer. Bektu contacts them on your behalf and sends you a scored report. They never see who asked.
Search and verify any developerMore from Bektu
Stay a step ahead of the wire transfer
Get the occasional note from Bektu on verifying developers before you commit. No noise, just what matters.
We will never share your email. You can opt out at any time.