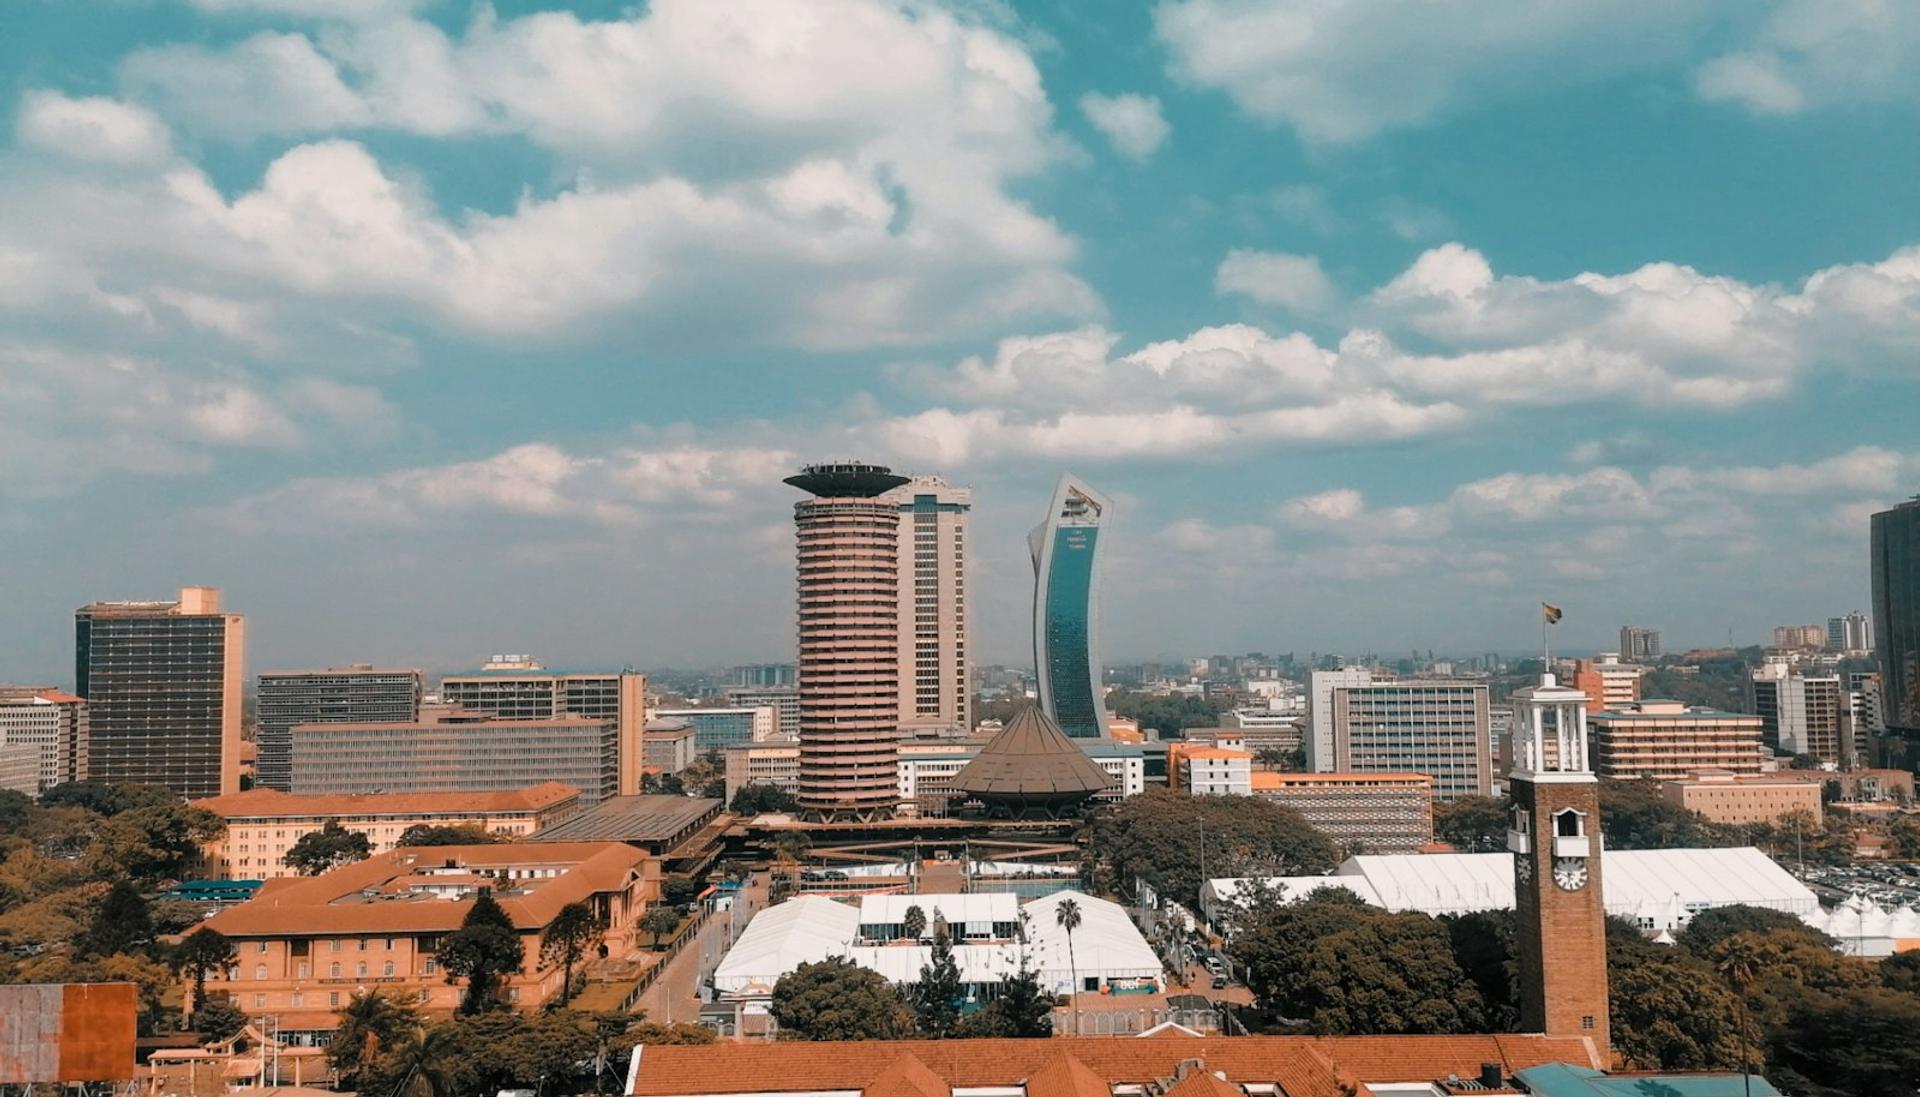
Kenya's Mortgage Market Holds Just 30,762 Accounts as Average Rate Falls to 13.5 Percent
Kenya's entire residential mortgage market held just 30,762 loan accounts at the end of December 2025, according to the Central Bank of Kenya's Bank Supervision Annual Report 2025, released this week. The outstanding book grew 10 percent to KSh307.2 billion from KSh279.3 billion, but the number of borrowers rose by only 746 accounts, and non-performing mortgage loans climbed to KSh50.2 billion from KSh46 billion.
What it means for a foreign buyer
This survey counts resident borrowers at Kenyan banks, not foreign purchasers, and most non-residents will never appear in it. It still sets the terms you buy under. A market of 30,762 mortgage accounts in a country of more than 50 million people means there is almost no financed resale demand, so when you come to sell, your buyer will almost certainly be paying cash or drawing on diaspora savings. Price your exit on that basis rather than on the assumption that a mortgage market will carry the next owner. The average loan is now KSh10 million, roughly the price of a mid-market Nairobi apartment, which tells you where the thin band of financed demand actually sits: above that level you are selling into an all-cash pool that is far smaller again.
The rate numbers cut the other way. Average mortgage pricing fell to 13.5 percent from 15.2 percent, and the spread across lenders ran from 7.5 percent to 19.6 percent, down from 8.2 to 20.4 percent a year earlier. A twelve-point gap between the cheapest and dearest lender is the single most useful figure in the release: if you are a diaspora buyer eligible for a Kenyan facility, quotes are not converging, and taking the first offer from the bank holding your existing account can cost you multiples of the arrangement fee. The rising bad-debt figure matters too. Non-performing loans now sit at KSh50.2 billion against a KSh307.2 billion book, a little over one shilling in six, and repossessed stock is the most common source of genuinely discounted Nairobi supply, in a market where prime home prices rose 6.2 percent in the first half of 2026 while rents barely moved.
Get written quotes from at least three lenders before committing to any one bank's in-house financing.
What changed
The comparison is year on year against December 2024. Outstanding mortgage debt rose 10 percent, from KSh279.3 billion to KSh307.2 billion. Banks advanced KSh27.9 billion in new mortgage lending over the year. Account numbers moved from 30,016 to 30,762, a rise of 2.5 percent, while the average loan size increased 11.1 percent from KSh9 million to KSh10 million.
That split is the substance of the release. Value grew roughly four times faster than borrower numbers, which means the portfolio expanded because existing borrowers took larger loans, not because the market widened. Average pricing fell 170 basis points to 13.5 percent, and both ends of the rate range came down, the floor from 8.2 to 7.5 percent and the ceiling from 20.4 to 19.6 percent. Non-performing mortgage loans rose 9 percent to KSh50.2 billion.
Companies in Kenya with the most evidence on file
Ranked by BektuScore, which measures how much a buyer can verify about a company from public records. It does not rate build quality or returns.
Superior Homes Kenya
Developer8 projectsNairobi, Kenya
75Bektu ScoreCentum Real Estate
Developer5 projectsNairobi, Kenya
75Bektu ScoreHome Afrika Limited
Developer3 projectsNairobi, Kenya
75Bektu Score
Considering a developer you read about here?
You cannot walk the land from another country. But you can verify the developer. Bektu contacts them on your behalf and sends you a scored report. They never see who asked.
Search and verify any developerMore from Bektu
Stay a step ahead of the wire transfer
Get the occasional note from Bektu on verifying developers before you commit. No noise, just what matters.
We will never share your email. You can opt out at any time.